Minggu, 14 Juni 2009

Do you think Direct Selling is SCAM?

It has been quite some time I’ve never had a chance talk to a direct selling person. Until recently, someone just started to approach me about direct selling. It is actually my neighbour insisted want to talk to me. I rejected at the first place but she told me that it isn’t anything about directly selling. Huh?


Me: What is it?
X: It is about a system.
Me: What system? Direct selling system?
X: No, it has nothing to do with direct selling. I’m going to introduce you a system. That’s why we need to talk. Can we meet tomorrow night to discuss in more detail?
Me: Some kind of the business? You want me to invest?
X: No, it is a system that I want to introduce you. So tomorrow night, okay?
Me: Okay, sure. (Just to give face since she is my neighbour. Don’t want to spoil our relationship)

What is My First Impression?


As what usually direct selling people do, they just want to talk to you no matter what. That is their first ultimate goal to approach their potential customers by not telling you first what they plan to sell you.
What the heck? You're selling stuff but you don't want to tell me what you're selling? Some more you lie... I dislike the ways they do things that doesn’t have the integrity at all. In the conservation as you can see, she kept avoiding my questions.


Conversation at that Night
Me: So, let’s start. I’m very curious about the system that you mentioned yesterday that has nothing to do with direct selling.
X: Yes, have you heard of a system?
Me: Huh? What kind of a system?
X: Before we start, you seem like you don’t like direct selling. Would you tell me why? (not answering my question again...)
Me: Yes, I can’t sell. That’s why I don’t like to sell stuff because this is simply not my strength. Unless the product is very good, then I probably can sell.
X: I see. If you don’t like to sell, you can just refer the product to someone else. For example, when you use a very good product and you definitely will share it with others, right? You don’t need to sell at all.... (Blah blah blah…. for few minutes)
Me: Yupe, you’re right. So, what is the “System” about? (not yet answering my question again about the system)
…
  • We talked about all these non-sense for about 30 minutes back and forth and she had not yet explained to me what the system is about.
  • She asked a lot of questions like where I buy my toothpaste, my grocery and etc. Then later she started talking about product that directly from the producer to consumers without those advertisement and etc.
  • Hey, isn't that all about direct selling right that they usually claim that their products without the charges of marketing, stocking, profit and etc?
Me: So, what is the system? I know about all these, what you have been saying so far it seems like a direct selling to me. What do you mean by system at the first place?
...
  • She started to explain the benefits of joining the direct sell company and how to enjoy the benefits from collecting a point.
  • This takes another 15 minutes and I stopped her half way immediately.
Me: So, this is a direct-selling "SYSTEM" in your company? So is this what you meant by the "SYSTEM" where you can also collect points and use that points for certain benefits?
X: “Hmm… kind of yes, As you see the "SYSTEM" is very powerful”. (she continued to talk about the "SYSTEM’s crap….)
Me (In My Thought Only): Why you don't want to tell at the first place? Why don't you just say the following:
  • Our company has a new system which his a totally different concept than the conventional direct-selling company. Do you want to hear about it in detail, maybe you're interested?

Is direct-selling scam?
As you probably know, direct selling is not a scam legally. It is a multi-level marketing (i.e. MLM) business with real products. Those pyramid scheme companies (e.g. swisscash) without the real products are only considered illegal. Although they’re not SCAM legally, the way the agent approaching me at least does look like a SCAM to me due to the fact that they have low integrity and unprofessional. What do you think?


Conclusion

I really don’t like most of the direct selling people (of course not all of them). They do not “STRAIGHT to the POINT” and talk a lot (really a lot) before go directly to the point. Their real intention deeply in their heart is want you to become their down line member rather than helping you to buy the right products that you really need.

At the end of our meeting, she did mention that buying direct sell products is actually cheaper and in fact we can save a lot and we can enjoy high quality of the product at the same time. It is cheap with good quality. I told her, if this is really true, I will 100% support your product! I really do…

What do think about direct selling or multi-level marketing? Do you think they’re SCAM?

Sabtu, 06 Juni 2009

Simple Way to Explain “Rule of 72”

Perhaps the most useful financial formula is the “Rule of 72”. It is a simple way to “estimate” how long it takes to double your money without using the complex financial formula.

However before you even want to know about this rule of 72, the fist thing you want to know is the compound interest. This is due to the fact that, this rule only applicable for your investment that based on the compound interest (which means you reinvest your interest return into your principal).
72 / Interest Rate (p.a.) = Years to Double Your $
Example 1: Investment
How much I can double my investment return of $10k with 8% interest?

Answer 1:
72 / 8% = 9 years.

If you’re now 25 years old, you will have $20k at the age of 34 years old.

Example 2: Inflation
I spend $2k per month. How long that my spending will inflate until $4k with my personal inflation rate of 2%?

Answer 2:
72 / 2% = 36 years.

If you’re now 25 years old and when you’re 61 years old later, you need to have at least $4k for your monthly spending.

Example 3: Goal Setting 
I’m now 30 years old and I have $100k cash now to invest. I want to have $200k in 2 years time. What is investment return that I should get to reach my goal?

Answers 3:
72 / 2 years = 36%

So if you want to earn the extra $100k in 2 years time, your investment return is expected to have at least 36% returns.

Summary
Rule of 72 gives you a quick estimation on what my interest rate should be or how many years that I need to double my return. It applies to anything that as long as it is based on the compound interest principle (e.g. inflation, saving, investment and even goal setting). Hope this helps.

Jumat, 29 Mei 2009

Why Compound Interest Is So Powerful?

In fact, it is nothing that really powerful about compound interest even though Albert Einstein has quoted the following:
“Compound Interest is the greatest force in the world”
Einstein, are you sure about that? The compound interest itself is not powerful but it is the human mind or emotion to make it the powerful one. If I were to say, what the greatest force in the world is, I will say it is “Human Mind” – our mind. Why the compound interest can become so powerful is due to the fact that:
“We do not know how it REALLY works or we simply IGNORE it!”

How Compound Interest Works?

Compound interest simply means to REINVEST your investment return into your total investment amount. Total investment amount is called PRINCIPAL in personal finance. Let’s say I invest $100 with 10% return. The investment return is $10 and I used back this money to reinvest, so my total investment or new principal value is now becoming $110. Second year, I reinvest at $121 (new principal amount). In following years, my investment return grows exponentially…

Note: Compound interest is also applicable to loan or mortgage interest. E.g. Your loan principal amount will grow exponentially if you don’t reduce your loan principal.


The Key is Exponential Growth

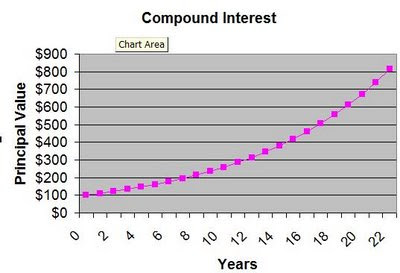
Your principal grows exponentially with the compound interest, that is how the magic works and that’s why we like to say it is powerful. Looks at the chart below:


In 7 years, I can X2 my money - ~$200 (see also Rule of 72). In 12 years, I can X3 my money - ~$300. In 15 years, I can X4 my money - ~$400. In 17 years, I can X5 my money = ~$500. In 19 years, I can X6 my money - $600. As you can see, the longer term I have the, shorter the period that I need to double-up my money. Can you see this MAGIC?

This is usually how those insurance agents use this magic to convince or trick you to buy their insurance especially for those non-term insurance policy.

In personal finance, everything is about compound interest whether you have car loan, housing loan, credit card loan, invest in stocks, unit trust, fixed deposit or the most important element in personal finance– inflation rate. 

Summary
Compound interest is really that powerful by itself or we don’t understand it that makes it powerful or we ignore it that makes it powerful? What do you think?

Jumat, 15 Mei 2009

Dollar Cost Averaging is Stupid?

It is funny that some people actually say that the “dollar cost averaging technique” (also known as DCA) is a stupid method. They start “giving up” using this technique especially when they make a lost in investing in Unit Trust or Mutual Funds.
“Dollar cost averaging is stupid! It doesn’t work and so far I have made a lost -30% out of my unit trust investment. What the heck? I should buy low and sell high, that’s the perfect technique!”
I used to heard of this kind of statement and RECENTLY getting more and more due to fact that the recent economy recession caused by the subprime crisis that most unit trust or mutual fund make a lost around -20% to -30%. More and more people start complaining about this “Dollar Cost Averaging” method is stupid and they regret to follow this technique which they used to believe that it is 100% guaranteed method as told by their agents. 100% guaranteed? Who told you that?


Dollar cost averaging is not stupid, okay?

Technically dollar cost averaging is NOT stupid but it was designed for STUPID people if you insist me to use the “stupid” word. So if you think you’re not stupid – know exactly when to sell high and buy low, don’t use Dollar Cost Averaging method. If you do, then you’re really stupid because Dollar Cost Averaging method is not designed to be used this way especially when you know when to sell high and buy low. So, do you think you're stupid or not?


What is the purpose of dollar cost averaging?

Dollar cost averaging is designed to be used by stupid people who doesn’t know exactly when to sell high and buy low. Also, this technique is designed for Long Term Investment Strategy – 5 to 7 years for example. If you’re using this method as a short-term investment strategy, then you use it for the wrong purpose. So now the question is - do you know when to sell high and buy low? Do you know the market goes up or down tomorrow? If you don’t know, use dollar cost averaging. But, would DCA guarantee Return of Investment (ROI)?


How dollar cost averaging works?

It is a very simple technique that you just need to invest fixed amount of money periodically (usually monthly). You can apply this whether to stock or unit trust or any kind of investment. This technique basically forces you to:
  • Buy MORE units investment at lower prices
  • Buy LESSER units investment at higher prices.
This is in a way to reduce your risk during market downtrend. When market goes down you buy even more units. As long as the market goes up again in the future, you will earn. But of course if the market never goes up, you will keep losing and that’s the whole point the dollar cost averaging is for long term investment strategy which you believe the market will go up in long run.


When you want to use dollar cost averaging?

Obviously, when you think you’re stupid you use this method. Because of this method is designed for stupid people like you and me, therefore once you’re start using this method, you’re not considered as stupid anymore – you’re smart!

Here you go the reasons when you should use DCA:
  • Don’t know when to sell high and when to buy low. You can use one lump sum investment strategy if you know exactly the lowest and the highest of the market
  • Only if you BELIEVE your investment will goes up in long term - 5 to 7 years or even more years. If you intent to use DCA for short term investment, let’s forget about it
  • Continue to use DCA even during market downtrend. Don't stop or complain about DCA method when you make a lost in investment. DCA is designed for you to even to invest more (buy more units) during market downtrend. Unless, you're kind of sure that the market will never be recovered again, you can give up DCA method then.

Summary

Dollar cost averaging is in fact a perfect method to guarantee the investment return as long as the market or stock or unit trust that you buy goes up in long run. Most importantly it reduces the risk when the market goes down and you can earn back your investment when the market goes up again. 

How can this perfect method being perceived as a stupid? Don’t fall into the common trap that does not understand the purpose of DCA method. Use a right method for a right purpose is SMART, use a right method for a wrong purpose is STUPID. Don't you think so?

In personal finance, as long as we do it right we can be as stupid as possible. That's is something FUN about personal finance. Have fun!

Jumat, 01 Mei 2009

Tax Relief Tips for Critical Illness Life Insurance in Malaysia

Few days ago, I had supper with some old friends and I realized that many of them do not aware that they can actually claim the "36 critical illness" life insurance under ‘Medical Insurance” category when they’re filling for tax. But it is already too late for them, maybe for you too? I think this is worth to share with you guys ...

If you buy the "36 Critical Illness" life insurance from Great Eastern or they probably call it "Supreme Livin’Care Plus", you can claim up to 60% of your total premium paid under the education and medical insurance category (limit is RM 3000). However, of course you also can claim up to 100% of your total premium paid under life insurance and EPF category (limit is RM 6000).

Many people think that this critical illness life insurance can only be considered as life policy for tax relief but this is not true. It can be considered as medical policy as well for tax relief. Sometimes especially when you have fully utilized the RM 6000 limit (life and EPF), you can still claim the 60% under the medical insurance. At least this is true for Great Eastern and I'm not sure other insurance companines. 

When you receive the tax relief statement from Great Eastern every year, it basically categorizes the insurance into 4 categories (stated at the back of your statement):
Life
100% of premium paid are eligible for tax relief as life policy

Education/Life
100% of premium paid are eligible for tax relief as education or life policy

Medical/Life 
60% of premium paid are eligible for tax relief as medical policy. 100% of premium paid are eligible for tax relief as life policy

Medical
100% of premium paid are eligible for tax relief as medical policy.
The "36 critical illness" life policy or the "supreme livin'care plus" life policy in Great Eastern is categorized under Medical/Life. If you missed it this round, don't make a same mistake next year. Hope this helps. :D

Sabtu, 21 Maret 2009

How to calculate housing and car loan interest?

Perhaps you may not aware the way our car loan interest and the housing loan interest are calculated differently.

Housing loan interest is calculated based on the principal of the loan that you have and the interest is not fixed. Principal of your loan is the amount of money that you still owe the bank.

Car loan interest is calculated based on the total amount of loan that you have and the interest is fixed.


Housing Loan

For example, you borrow $50K from a bank at 5% interest rate for 5 years.

1 year housing loan interest:
  • $50K X 5%
  • $2,500 (Yearly)
First month housing loan interest:
  • $2,500 / 12
  • $208.33 (First Month)

Depending on the monthly installment amount that you have, let’s say $1K per month, you will reduce your principal from $50K to:

Renew Principal $ after first payment:
  • $50K – ($1K - $208.33)
  • $49,208.33 (New Principal)
The second month interest will then be calculated based on this new principal amount, $49,208.33 and every month you will be reducing your principal amount.

Second month housing loan interest:
  • $49,208.33 X 5% / 12
  • $205.03 (Second Month)
Let’s do the math by yourself using excel or use the following housing loan calculated, that you’re will end-up to pay $943.56 monthly and the total interest paid is $6613.70

Total car loan interest rate:
  • $6613.70 / $50K X 100%
  • 13.23% (Total Housing Loan Interest Rate)

Car Loan

On the other hand, you have car loan of $50K at the interest rate of 5% for 5 years term.

1 year car loan interest:
  • $50K X 5%
  • $2,500. (Yearly)
First month car loan interest:
  • $2,500 / 12
  • $208.33 (First Month)

The only difference between the housing loan versus car loan is the car loan interest rate is fixed for every month. Therefore:

First month car loan interest:
  • $2,500 / 12
  • $208.33 (Second Month)
Let’s do the math again and the total amount that you want to pay including the interest for the entire loan is ($50K + $2,500 X 5 years) = $62,500 and monthly payment will be ($62,500 / 5 / 12) = $1,041.66 


Total car loan interest rate:
  • ($2500 X 5 years) / $50K X 100%
  • 25% (Total Car Loan Intereset)
As you can see the car loan interest is 1.9 X higher than housing loan interest (i.e. 12.23% X 1.9 = ~25%) 

Conclusion

Because the car loan does not reduce the principal amount and the interest is fixed through the year, therefore the interest is higher than the normal housing loan interest calculation provided the interest rates are the same.

So usually what people do when they have housing loan is try to reduce the principal amount as early as possible either by flexible-loan package or early extra payment. It doesn't work for car loan because the interest is fixed and the total interest that your are going to pay is 1.9 X higher than housing loan interest.

You may also want to know that the car value is depreciating every year after you buy it. Think of it, is this making sense to buy a car or house?

Sabtu, 14 Maret 2009

Tax Deduction Incentive for Property – Should I go for it?

The recent news for Malaysian that they may now eligible to claim up to RM10K tax deduction for the loan interest that they pay. I have summarized this news below:
  • Applicable to all types of properties (i.e. landed house, flat, apartment or condominium)
  • Applicable to those who buy the property between March 10, 2009 and Dec 31, 2010.
  • Applicable to one property only and to those who buy the property for living (non-rental) purposes only.
  • If you’re eligible, you can enjoy this tax deduction incentive for 3 consecutive years.
So, the question now is should we buy property during this economy crisis especially with this kind of incentive?

Few things that you may want to consider:
What if the property value drops after you buy it? Isn’t that possible during this bad economy?

[In my opinion]: I don’t think it will drop. Worst come to worst if it drops, I believe in long term the property will still appreciate down the road. If you scare, you have till Dec 31, 2010 and you can still wait and see the market condition before making any decision.

What if the developer cannot finish the construction as promised after your down payment?

[In my opinion]: Yes, I do think this can happen especially for those not reliable developers. Even for the reliable one, we need to be careful also during this bad economy. So if I were to buy, I would prefer to buy those existing finished construction properties. I don’t dare to buy any still under-construction property, do you?

Summary

If you’re jobless now or financially not stable, I don’t think you should buy any new properties for the sake of this incentive program. If you have already planned to buy property for quite some times and you’re not jobless now and financially stable, I think you should definitely make use of this tax deduction incentive. Good luck!